09-21-2026


|
Getting your Trinity Audio player ready...
|
The views expressed in this article are those of the author and do not necessarily reflect the position of CoinGeek.
TL;DR: The Senate rejected the CLARITY Act, but the SEC and CFTC moved quickly to provide clearer paths for digital asset innovation, including tokenized stocks, self-custodial wallets, passive software, and public permissionless ledgers.
Key Takeaways:
- The U.S. Senate rejected a motion to advance the CLARITY Act by a 49–50 vote.
- The SEC announced an innovation exemption allowing certain tokenized stocks to trade on-chain.
- The SEC said smart contracts used by tokenized securities venues must be auditable, public, and deployed on a public, permissionless ledger.
- The CFTC issued no-action relief for providers of passive software, including self-custodial crypto wallet software.
- SEC and CFTC actions provided regulatory relief for certain digital asset software and tokenization activities despite the CLARITY Act’s failure.
Brief History: The CLARITY Act (H.R. 3633) is a U.S. bill introduced in 2025 to establish a clearer regulatory framework for digital assets and define the roles of the SEC and CFTC. It passed key House committees in June 2025 and advanced to House consideration in July.
Table of Contents:
- CLARITY fails as regulators move ahead
- Republicans and Democrats make their cases
- Who really needed the CLARITY Act?
- Regulators moved to fill the gap
- Could the next SEC chair reverse all of this?
- Put BSV at the center of it
- FAQs
On September 15, a little after two in the afternoon, Washington time, the Senate votes on whether to even begin debating the CLARITY Act, the crypto market structure bill the House passed 294 to 134 back in July 2025. Cloture needed 60. It got 49. Fifty senators voted no, every Democrat plus a few Republicans, per the Senate Cloakroom tally.
Reporter Eleanor Terrett posted a text from an industry leader within minutes: “It died.”
Ted Cruz reached for The Princess Bride: “There’s a big difference between dead and mostly dead. I hope it comes back to life.” John Kennedy skipped the eulogy and went straight to scheduling the burial: “But it’s gonna have to wait until the lame duck session.”
The bill is dead, and it never mattered. Bitcoin never needed CLARITY, and neither did anyone building anything real. In the 48 hours after the vote, the SEC and the CFTC handed builders the keys anyway.
Both parties, receipts on the table
Republicans first, because they earned it.
Cynthia Lummis spent the run-up posting that Democrats had been handed “120+ wins” and were still hunting for a way to vote no. Tuesday morning she set the deadline.
It was never. She told reporters that if cloture failed, “I think we’re done. It’s over.” Then it failed, and by Thursday, she was posting that the bill delivered the insider-trading authority Democrats had asked for and that “Democrats voted no anyway.” True, but a grievance is not a plan.
Now the Democrats, in their own words. Elizabeth Warren, crypto’s least favorite senator, on Tuesday: “Senate Republicans are trying to jam through a crypto bill that would let Trump continue lining his pockets off the crypto industry.” Ruben Gallego: “all President Trump wants is for the Senate to give him time to crime, and I won’t support any piece of legislation that enables him.” And Kirsten Gillibrand, who negotiated this bill for months and then voted it down, on Wednesday:
And my Republican friends can grit their teeth, because on the receipts, the Democrats have a point.
$TRUMP launched on January 17, 2025, three days before the inauguration. $MELANIA followed two days later. In May 2025, the top 220 holders of the President’s memecoin got dinner at his golf club, per CNBC and NPR. Reuters estimated in June 2026 that the family’s crypto ventures generated $2.3 billion in profit between mid-2024 and April 2026, with the memecoin alone accounting for about $1.2 billion in token sales. World Liberty Financial, the family’s flagship, got preliminary OCC approval to become a bank in August 2026, per the Wall Street Journal. Steve Witkoff, the President’s Middle East envoy, reported more than $100 million from the entity holding his World Liberty stake, per the Journal in September 2026.
None of that is an allegation so much as a reading of the disclosure forms.
Then there is the Tether door, which I already walked through in July. Commerce Secretary Howard Lutnick ran Cantor Fitzgerald (NASDAQ: ZCFITX), the firm that manages Tether’s assets, and bought the right to a 5 percent stake in Tether through a $600 million convertible bond in April 2024, per Bloomberg. Bo Hines, as the White House crypto aide, held the GENIUS Act’s three-year grace period as a red line when Democrats wanted 18 months. Trump signed GENIUS on July 18, 2025. Tether announced Hines as its Strategic Advisor for Digital Assets and U.S. Strategy on August 19, 2025. ONE MONTH. Hines spent Wednesday posting about USAT from an X account whose bio reads “Tether.”
I don’t care who you voted for. Those people and those dates are why the bill is dead. Moving on.
So, who actually needed this bill?
Not Bitcoin.
Bitcoin has been a commodity under the Commodity Exchange Act (CEA) at the Commodity Futures Trading Commission (CFTC) for a decade, and it never needed a statute to say so. Gary Gensler, of all people, put it in writing: the January 2024 spot ETF approval was, in the SEC’s own words, “cabined to ETPs holding one non-security commodity: bitcoin.” When Gensler concedes your asset is a commodity, the argument is over.
So what was CLARITY for? The altcoin casino: a federal permission slip for token issuers, centralized exchanges, and the venture funds behind both. I said as much in June 2025, when the treasury companies were being born, and the loudest cheerleaders for this bill were the same people running that playbook.
Builders never needed a permission slip. Builders needed the cops to stop kicking in doors. That part already stopped, and this week the cops started posting about it.
Then the agencies got to work
Tuesday night, hours after the vote, Tim Scott, the Republican chairman of the Senate Banking Committee, told the agencies to write the rules without him.
A Banking chair who just lost a floor vote is telling two agencies to go ahead without Congress, which is not the posture of a man waiting for the lame duck.
Just after noon on Wednesday, SEC Chairman Paul Atkins answered him.
“Stay tuned” lasted about 21 hours. On Thursday morning, the SEC published its Innovation Exemption, an order allowing certain tokenized stocks to trade on-chain, and Atkins’ written statement opens by naming the corpse: “Earlier this week, Congress was unsuccessful in advancing the CLARITY Act despite the tireless efforts of many.” One condition in SEC release 2026-90 deserves a frame on the wall: “Smart contracts used by a TSV must be auditable, public, and deployed on a public, permissionless distributed ledger.”
Public. Permissionless. Auditable. Somebody at the SEC has been reading the whitepaper!
Commissioner Hester Peirce needed seven words.
Her written statement went further than the order, and this is the sentence every BSV developer should tape above the monitor: “An investor does not need an exemption to avail herself of permissionless smart contracts that mediate peer-to-peer trading.” The exemption is for intermediaries; permissionless software was never the problem.
The funniest thing I dug up all week: Peirce’s remarks to the SEC’s Investor Advisory Committee on September 10, five days before the vote, were titled “Lame Duck,” because her term is ending. Her closer: “I may be a lame duck, but I am looking forward to seeing how you help future Commissions keep their ducks in a row.” Five days later, the lame duck argument killed the bill, her own agency then routed around… Heck of a week to be a lame duck!
The same Thursday morning, the CFTC put its own green light on the pole.
Staff Letter 26-25 takes relief the CFTC granted one wallet developer in March 2026 and opens it to every provider of software that does not “take into custody User assets, generate express “buy” or “sell” signals, or exercise discretion with respect to the routing or execution of User orders.” Self-custodial digital currency wallet software is named in the letter. And footnote 14, for the people in the back: “For the avoidance of doubt, PSPs are not limited to providers of crypto asset related software.”
That letter sits on top of the April 13, SEC staff statement that self-custodial wallet interfaces are not broker-dealers, on top of Atkins’ August 18 startup and fundraising exemption proposals, and on top of CFTC Chairman Michael Selig’s August line: “We’ve crossed the Rubicon and are standing at a new frontier of finance.”
The bill died on Tuesday. The green lights went up on Thursday.
Can’t the next SEC chair just undo all of this?
Yes.
Atkins said it himself in August: legislation “remains indispensable” to protect this work “from being unwound by a future rogue regulator.” An exemption is a favor from the current occupant. Occupants change.
But the favor only covers the people who need favors. A no-action letter protects an intermediary. An exemption protects a venue. Peirce spelled out the escape hatch herself: “Truly decentralized systems that are driven by automated software do not give rise to the foundational concerns underlying securities regulation, namely that an intermediary you trust to act on your behalf will be foolish, careless, or compromised.” A protocol that needs no intermediary needs no letter, and nobody can revoke a letter you never needed.
Which is exactly why the smart play this fall is to build on the one chain that does not depend on the exemption at all.
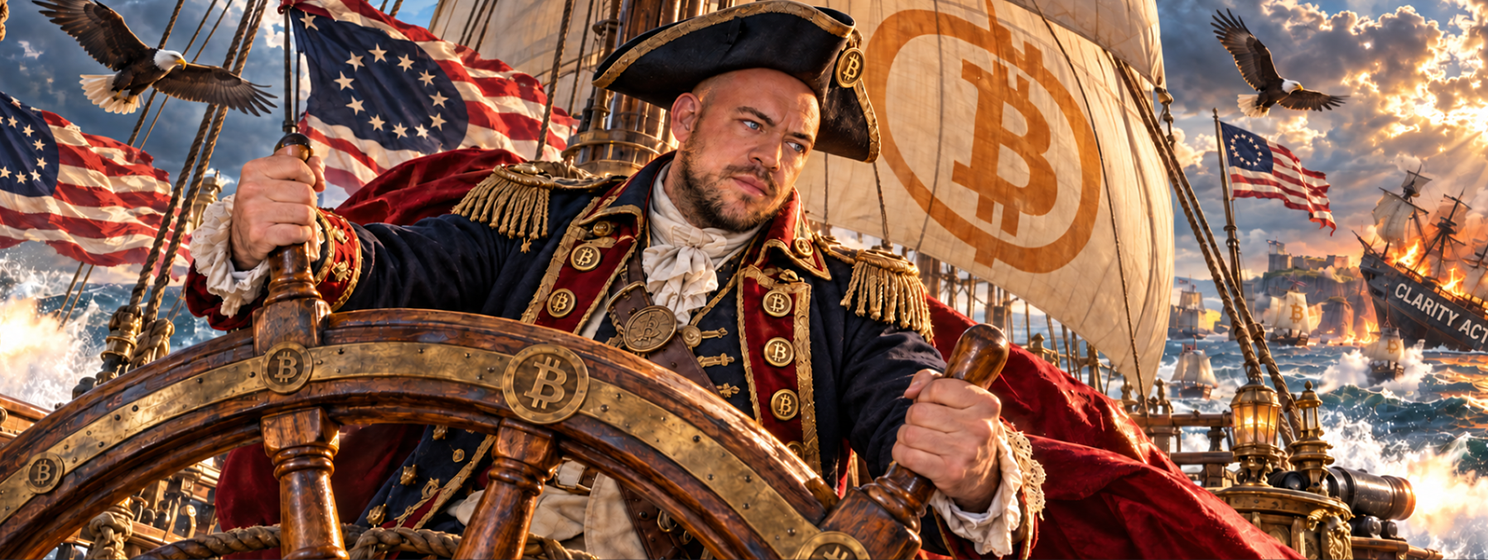
Make BSV red, white and blue
Between them, the SEC and the CFTC spent the week describing passive software, self-custodial wallets, a public, permissionless ledger, auditable smart contracts, and peer-to-peer trading with no one in the middle.
That is less a wish list than a spec sheet for BSV as it exists on September 18, 2026.
So allow me some shameless self-promotion, which is also just the roll call. GorillaPool, where I serve as the highest-ranking human officer, runs a permissionless mining pool, the JungleBus indexer, a Teranode implementation, ARC broadcast, and the 1Sat Ordinals index. Open Protocol Labs and bOpen build agents and open-protocol infrastructure that businesses own instead of renting. Project Babbage, Ty Everett’s shop, ships the Metanet stack and the BRC-100 wallet standard, an open API that lets any BSV app talk to any compatible wallet, which is the exact shape of “passive software” the CFTC just blessed. And a bench of independent builders, I will let name themselves.
Shameless? Sure. Also correct.
We are the Americans ready to make this work on BSV!
So while Washington waits on its lame duck, the builders get to march. Ship the wallet software. Build against BRC-100 so every app works with every wallet, and nobody has to take custody. Put the smart contract on a public, permissionless ledger, exactly as the SEC just said it must be. Tokenize the thing your customer actually wants and route it through code instead of a venue. Do it in America, and say so out loud, because the CFTC chairman just told you the only open questions are where the innovation happens and who writes the rules.
The altcoin casino needed CLARITY, and it will spend the next three months begging for a lame duck resurrection. Bitcoin never needed it. Builders never needed it. The permission slip is dead, and the road was open the whole time.
Let’s make it red, white, and blue!
FAQs:
What happened to the CLARITY Act?
The U.S. Senate rejected a motion to advance the CLARITY Act in a 49–50 vote, falling short of the 60 votes needed.
What did the SEC do after the CLARITY Act failed?
The SEC issued an Innovation Exemption allowing certain tokenized stocks to trade on-chain under specific conditions.
What did the CFTC announce?
The CFTC issued no-action relief for passive software providers, including self-custodial crypto wallet software.
What are the SEC’s requirements for tokenized securities?
Smart contracts used by covered tokenized securities venues must be auditable, public, and deployed on a public, permissionless distributed ledger.
What happened to crypto regulation after the Senate vote?
The SEC and CFTC took separate actions addressing tokenized stocks, passive software, and self-custodial wallets despite the CLARITY Act failing to advance.
This opinion piece is published to encourage discussion. The author’s views are their own and do not constitute legal, procurement, or policy advice, nor do they represent the positions of CoinGeek or its partners.
Watch: What Happens When Blockchain Becomes Invisible?